Capital Gains Tax on Agricultural Land Sale in India
Understand how capital gains tax applies to agricultural land sales in India, when rural land is exempt, and how to save.

- Rural agricultural land is not a capital asset under Section 2(22)(iii) of the Income-tax Act, 2025 (Section 2(14)(iii) of the 1961 Act). Its sale attracts no capital gains tax.
- The rural test is mechanical: census population of the nearest municipality, and aerial distance of 2 km, 6 km or 8 km.
- Urban agricultural land is taxed like any immovable property. Long-term starts at 24 months.
- Section 83 of the Income-tax Act, 2025 (Section 54B of the 1961 Act) needs two years of actual farming and locks the new land in for three years.
When Does Capital Gains Tax Apply on Agricultural Land?
Whether you owe capital gains tax on agricultural land comes down to one question: is the land rural or urban under the Income Tax Act
Rural agricultural land is excluded from the definition of a capital asset by Section 2(22)(iii) of the Income-tax Act, 2025 (earlier 2(14)(iii)). No capital asset means no capital gain, and no capital gain means nothing to tax. Urban agricultural land gets no carve-out and is taxed like any other capital asset. The Income-tax Act, 2025 replaced the 1961 Act from 1 April 2026; for sales completed before then, the old section numbers apply.
Two owners can sell what looks like the same plot, and one pays nothing while the other owes tax on the whole gain, purely because of where the land sits.
Rural vs Urban Agricultural Land
The classification has nothing to do with how the land is farmed. It is a test of location and population.
Land is rural if it sits outside the jurisdiction of a municipality or cantonment board with a population of 10,000 or more, and outside these aerial distances from those limits:
2 km, where the population is above 10,000 and up to 1 lakh
6 km, where the population is above 1 lakh and up to 10 lakh
8 km, where the population is above 10 lakh
The population comes from the last published census. Distance is measured aerially, not by road.
Land inside those limits is urban agricultural land, taxed as a capital asset.
The exemption attaches to the land itself. A farmhouse, well, or standing trees sold in the same deal are valued separately.
How Rural and Urban Agricultural Land Affect Capital Gains Tax?
Rural versus urban decides your taxes. A second classification decides whether the claim survives scrutiny: whether the land was actually farmed.
Revenue records maintained by the concerned revenue authority often record seasonal cultivation details. These records help establish whether agricultural operations were actually carried out, particularly when claiming exemptions under the Income Tax Act. Section 83 (earlier 54B) also relies on evidence that the land was used for agricultural purposes during the prescribed period.
How to Calculate Capital Gains Tax on Agricultural Land
Capital gains tax on agricultural land is the tax on profit earned when selling it, calculated as sale price minus purchase cost and expenses. Rural agricultural land in India is tax-exempt, while urban land is taxable as a capital asset, unless the gains are reinvested in new farmland within two years to claim exemption under Section 83 (earlier 54B).

Rural Agricultural Land vs Urban Agricultural Land for Capital Gains Tax
The table below sets the two classifications against each other on status, tax and provisions.

Exemptions and Ways to Reduce the Liability
Section 83 (earlier 54B) lets individuals and HUFs claim exemption on capital gains from agricultural land by reinvesting in new agricultural land within two years, provided the original land was farmed for two years before sale. Unreinvested funds must be deposited in a capital gains account scheme before the tax return due date, and the new land carries a three-year lock-in.
Section 85 of the Income-tax Act, 2025 (Section 54EC of the 1961 Act) offers an alternative for long-term gains, allowing investment within six months in bonds issued by NHAI or REC, or other bonds the Central Government notifies.
Other Taxes That Can Show Up Alongside This
Section 393(1) (Table Sl. No. 3(i)) of the Income-tax Act, 2025 (Section 194-IA of the 1961 Act) requires buyers to deduct TDS at the notified rate on urban agricultural land transactions, but rural agricultural land is expressly excluded from this provision.
NRI sellers fall under Section 393(2) of the Income-tax Act, 2025 (Section 195 of the 1961 Act) instead, which applies at higher rates than the standard TDS provision.
Section 78 of the Income-tax Act, 2025 (Section 50C of the 1961 Act) empowers tax authorities to treat the stamp duty value as the deemed sale consideration when urban agricultural land is sold below that value, subject to a tolerance margin.

How 1acre.in Helps
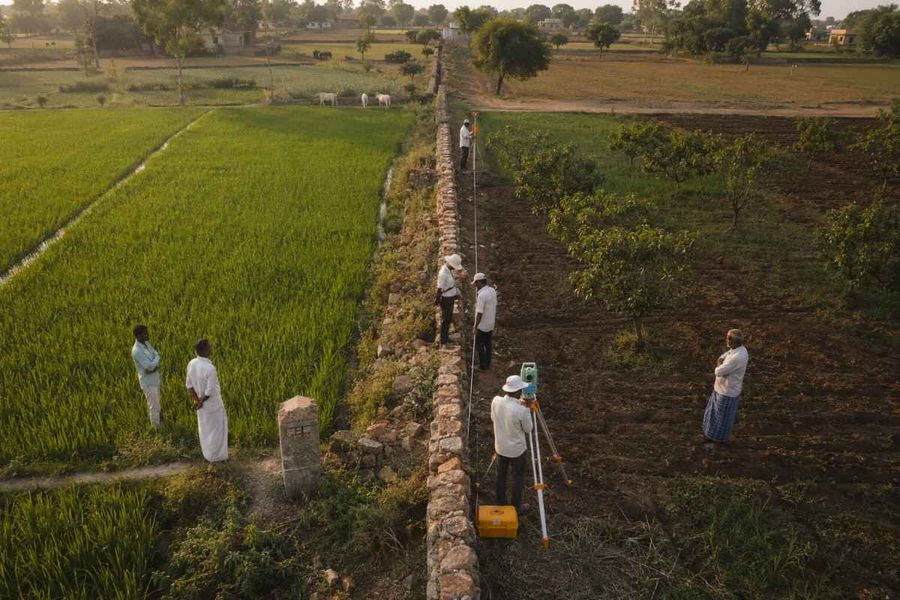
The rural test turns on distance from a municipal boundary, which is a mapping question before a tax question. 1acre.in overlays survey number maps and municipal and master plan boundaries onto its listings so you can see where a parcel sits against the nearest municipal limit.
A map shows distance and boundary. It does not confirm the census population figure, and it is no substitute for a chartered accountant where a few kilometers decide the outcome.
Conclusion
Capital gains tax on agricultural land depends primarily on whether the land qualifies as rural or urban under the Income Tax Act. Verify the land's classification early and plan any eligible tax exemptions before completing the sale to avoid unnecessary tax liability.
-900x600.jpg)
-900x600.jpg)
-900x600.jpg)
-900x600.jpg)